The short answer
Upgrading from HDB to condo is one of the biggest money decisions your family will make. Upgrading is worth it only if you can live comfortably with the payments after you move. Not on paper. In real life, with a bad year thrown in.
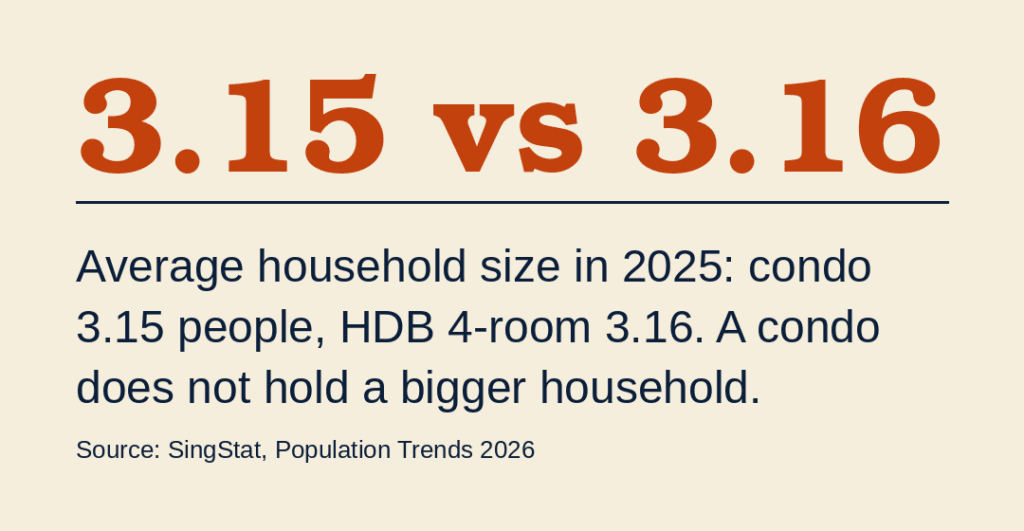
Stop assuming a condo gives you more room. In 2025, the average condo household (3.15 people) was the same size as the average 4-room household (3.16). If space is your reason, measure it.
And don’t tell yourself you can decide later for free. Bank loan rules are tied to age 65. From age 35, the later you decide, the shorter your loan and the higher your monthly payment. Prices matter too, but this data cannot tell you about them.
The data
These numbers cover resident households only (citizens and permanent residents). They are for 2025.
Household size by home type
| Home type | Average household size, 2025 (people) |
|---|---|
| Landed | 4.13 |
| HDB 5-room / executive | 3.48 |
| HDB 4-room | 3.16 |
| Private condos and apartments | 3.15 |
| HDB 3-room | 2.43 |
| HDB 1-room and 2-room | 1.92 |
The average condo household is no bigger than the average 4-room household. It is smaller than the average 5-room household.
More households live in condos now
- Private condos and apartments housed 17.9% of resident households in 2025, up from 13.9% in 2015.
- That is about 266,000 households, up from about 170,000.
- Condos have passed HDB 3-room flats (16.6% in 2025).
Source: SingStat, Population Trends 2026.
One limit: the report counts people per household. It does not compare floor areas by home type.
What it means
1. A condo does not hold a bigger household
The data shows condo households and 4-room households are the same size on average. It shows who lives where, not why they moved. My read: if you want a condo for space, don’t assume. Check the floor area. A condo can still be worth it for other reasons: location, facilities, privacy, or owning private property.
Those are fair reasons. But pick one and say it out loud. “It feels like the next step” is not a reason. If you can’t name what you want, you are not ready to buy it.
2. Everyone else upgrading is not a reason
The data shows the condo share of resident households rose from 13.9% to 17.9% in ten years (2015 to 2025). My read: the more people around you move, the stronger the pull to follow is likely to be. Ignore it. Your friends don’t pay your loan.
3. Your window is about loan years
The Monetary Authority of Singapore (MAS) sets a lower loan limit when a home loan for a private property runs longer than 30 years, or runs past age 65 (MAS). To get the higher limit, your loan has to end by 65.
A 30-year loan started at 35 ends at 65. So from age 35, waiting is not free. Each year you wait is one loan year gone. A shorter loan means a higher monthly payment for the same amount borrowed.
| Your age when you buy | Loan years to age 65 | Monthly payment, compared with a 25-year loan |
|---|---|---|
| 40 | 25 | The baseline |
| 45 | 20 | About 15% to 19% higher |
| 50 | 15 | About 40% to 52% higher |
Illustration only. It assumes the same loan amount and interest rates between 2% and 4% a year. It is not a forecast of interest rates.
People are also marrying later. SingStat puts the median age at first marriage at 31.1 for grooms and 29.6 for brides in 2025, up from 30.3 and 28.2 in 2015. My read: a later marriage likely means a later first home, and a later upgrade decision. That leaves fewer loan years when the decision finally comes.
What this data cannot tell you
It cannot tell you whether prices will go up or down. Prices matter to your decision, but the report has no price data, and I won’t guess. Neither should you.
If you have children in school
This decision lands on the whole family, not only the two names on the loan. The average 5-room or executive flat household has 3.48 people. The average condo household has 3.15 (2025). That counts people, not floor area. So if you are moving from a 5-room flat, compare the floor areas. Then make sure everyone at home can live with the answer.
A story from my work
A couple in their early 40s owned a 5-room flat. Their children were in school. Their fear was simple: becoming house-rich and cash-poor.
So we worked backwards. First, what they would keep from the sale after the CPF refund. Next, a monthly payment they could live with comfortably. Only then did we look at a price range.
They bought a smaller resale condo.
The lesson: the right upgrade is the one you can comfortably live with after the purchase.
What to do next
- Name your real reason. Write it in one sentence. Space, location, facilities, or owning private property. If it is space, compare actual floor areas, not home types.
- Get your family in the room. If you and your spouse give different reasons, settle that before you view a single unit.
- Start from what you would keep. Take your likely sale price. Subtract the loan you still owe and your CPF refund.
- Fix a comfortable monthly payment first. Use your own budget. The most a bank will lend you is a limit, not advice.
- Count your loan years. Take 65 and subtract your age. The most is 30. For a joint loan, ask your banker how the age is worked out.
- Test it on a bad year. Could you still pay on one income, or if interest rates rise? If not, that price is too high for you.
- Decide the order. Selling first or buying first changes your stamp duty and where you live in between. Check the current rates on the IRAS website.
- If it doesn’t work, stay. That is a good decision, not a failure. Look again in a year.
Questions people ask
Is a condo bigger than an HDB flat?
Not always. The report does not compare floor areas. It shows the households are the same size on average: 3.15 people in condos and 3.16 in 4-room flats (2025). Check the floor area of every unit you view.
Am I too old to upgrade at 45 or 50?
No. But your loan will be shorter if it has to end by 65, so the monthly payment is higher. If the loan runs past 65, the loan limit is lower, so you need more cash or CPF at the start. Ask your banker for the current limits.
Should I sell my flat first, or buy the condo first?
It depends on your cash and on stamp duty. Buying before you sell can mean paying extra stamp duty. Check the current rules with IRAS before you commit to either order.
Does this data mean condo prices will rise?
No. The report has no price data. It tells you who lives where, not what homes will be worth.
Sources
- SingStat, Population Trends 2026 (released September 2026). Household figures are for 2025 and cover resident households only. Household counts are computed from SingStat’s figures.
- Monetary Authority of Singapore, “MAS Restricts Loan Tenure for Residential Properties”, 5 October 2012. Checked on 3 October 2026.
- The monthly payment comparison is my own calculation, using the standard loan repayment formula.
General market information on this page was last updated on 3 October 2026.
Start with your own numbers
Your upgrade budget starts with what your current home is worth.
Request your home report: andyseng.me/your-home-report
Andy Seng (Seng Cher Chin) | PropNex Realty Pte Ltd | CEA Reg No: R058286J | Agency Licence No: L3008022J | WhatsApp 9002 1510